Nigeria does not suffer from a shortage of entrepreneurs. It suffers from a shortage of patient, appropriately priced capital that can help promising businesses survive the distance between an idea and a durable company.
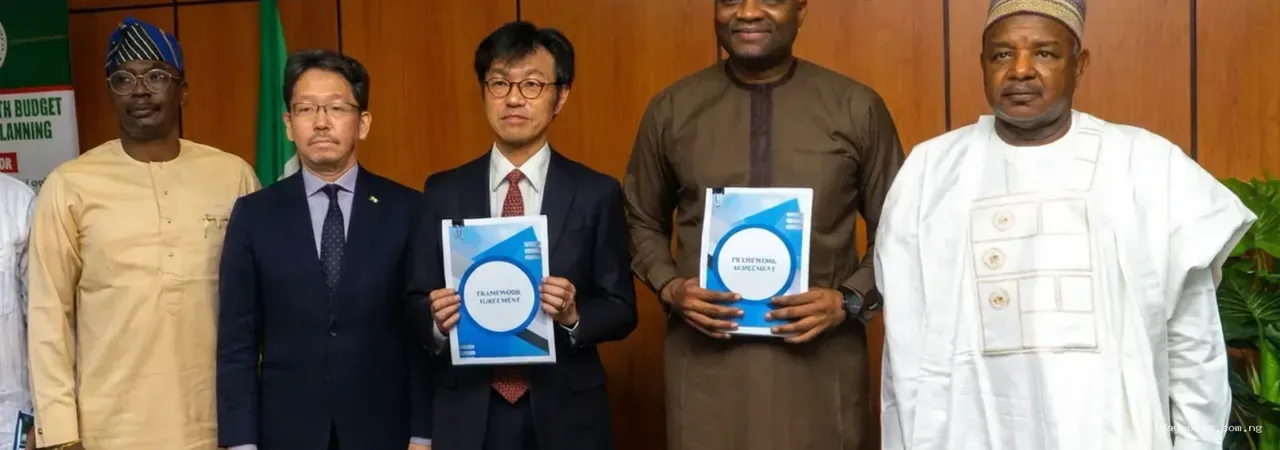
That is why the Federal Government's disclosure that it is working with the Japan International Cooperation Agency and the Nigeria Sovereign Investment Authority to establish six startup investment funds deserves attention. NITDA Director-General Kashifu Inuwa Abdullahi announced the initiative during the Global Tech Africa event in Kano, presenting it as part of a broader effort to deepen financing for innovative Nigerian businesses and strengthen the technology ecosystem.
The announcement is potentially significant. It is also incomplete. The funds are still being developed. Applications have not been announced. There is no verified public list yet showing the size of each fund, whether the instruments will be grants, equity, debt or blended finance, which sectors will qualify, or how investment decisions will be made.
Those details will determine whether the initiative becomes a serious financing platform or another policy announcement that founders cannot access.
Six funds should have six clear mandates
A common weakness in public financing programmes is that several funds are announced without clear differentiation.
If there will be six funds, each should have a defined purpose.
One might support early-stage technology companies. Another could focus on commercialisation of research. Another could finance growth-stage companies expanding across Africa. Another might support climate technology or industrial innovation. Another could provide debt for revenue-generating firms that do not want equity dilution.
The exact structure is not yet public.
The principle should be clarity.
Founders need to know which fund fits their stage and business model.
Grants, equity and loans solve different problems
A grant does not require repayment or ownership transfer, but it is usually limited and should support specific objectives such as research, prototyping or market validation.
Equity provides risk capital in exchange for ownership. It suits high-growth businesses where investors can wait for future value.
Debt requires repayment and is better suited to companies with predictable cash flow.
Blended finance combines instruments to reduce risk.
The government should not describe all of these simply as "funding". The instrument affects the founder's future.
NSIA involvement could bring investment discipline
The Nigeria Sovereign Investment Authority has a mandate that includes investing public capital professionally. Its involvement could help the programme avoid being treated as a political grant scheme.
That will depend on governance.
Investment decisions should be made by qualified managers under published criteria.
Political officeholders should not choose winners.
Every fund should have an investment committee, conflict-of-interest rules, audited accounts and performance reporting.
Public capital needs commercial discipline even when the policy objective includes development.
JICA brings another form of credibility
Japan's development agency can contribute technical expertise, institutional support and international networks in addition to money.
The strongest partnership would use JICA's involvement to improve fund design, monitoring and founder capability rather than merely placing a foreign partner's name on the announcement.
Nigeria should also learn from Japanese approaches to manufacturing, productivity and SME development, not only technology startups.
Innovation is broader than software.
The funds should not become Lagos-only programmes
Nigeria's startup ecosystem is heavily concentrated in Lagos, with growing clusters in Abuja and other cities. The Kano announcement is therefore symbolically useful.
But geographic inclusion requires more than holding events outside Lagos.
Application outreach should reach Kano, Kaduna, Jos, Enugu, Ibadan, Port Harcourt, Aba and other commercial centres.
Selection panels should understand regional business models.
Founders should not need a personal relationship with a Lagos venture-capital network to be considered.
Digital application channels can help, but ecosystem support also matters.
Traditional businesses can be innovative too
Nigeria often uses "startup" to mean a venture-backed technology company. That is too narrow.
A manufacturing firm using automation, an agricultural company developing cold-chain technology, a logistics business using data to reduce waste or a creative-industry platform building export tools can all be innovative.
The funds should define eligible innovation carefully.
If the programme supports only app-based companies, it may miss sectors where technology can raise productivity most dramatically.
Funding should be tied to measurable outcomes
Publicly backed investment should have a clear theory of change.
What is the programme trying to increase?
Jobs?
Revenue?
Exports?
Research commercialisation?
Female founder participation?
Regional inclusion?
Patents?
Productivity?
Private capital crowd-in?
The objectives should be measurable.
A fund that simply reports "50 startups supported" tells the public very little.
The selection process must be transparent
Founders need to know how to apply, what documents are required and how decisions are scored.
A credible process could include an initial eligibility screen, technical assessment, investment committee review, due diligence and final decision.
Applicants who fail should receive enough feedback to understand why where practical.
Selection should not be a mystery.
Mystery creates suspicion that connections matter more than business quality.
Nigeria should publish the managers before the money
Who will manage each fund?
Government agency staff?
Independent fund managers?
Private venture-capital firms?
NSIA?
A consortium?
Fund management determines investment quality.
Nigeria should choose managers based on track record, sector knowledge, governance and ability to support companies after investment.
A poorly managed fund can destroy value even with generous capital.
Follow-on funding matters
A startup may receive a first investment and still fail because no follow-on capital is available.
The six-fund architecture could be designed as a pipeline, with different vehicles supporting different stages.
That would be more powerful than six disconnected programmes.
A founder could move from prototype funding to seed investment and later growth capital based on performance.
The funds should also crowd in private investors rather than replace them.
Government should not protect weak companies from the market
Public financing can correct market failures, but it should not keep uncompetitive businesses alive indefinitely.
Startups fail.
That is normal.
The objective is not a zero-failure portfolio.
It is to invest intelligently, learn and produce enough successful companies to justify the risk.
Political pressure to avoid losses can make fund managers too conservative.
Political pressure to save every recipient can create waste.
Founder governance should be part of eligibility
Many startups fail because of poor governance rather than poor ideas.
Cap tables are unclear.
Founders mix personal and company funds.
Tax records are incomplete.
Intellectual property ownership is uncertain.
Employment contracts are weak.
Publicly backed funds should require basic governance standards and help founders improve them.
Money without institutional discipline can accelerate failure.
Women and underrepresented founders should have access without tokenism
Nigeria has many capable female entrepreneurs and founders outside established networks. Inclusive design should ensure they hear about the funds and can compete fairly.
That does not require lowering investment standards.
It requires removing unnecessary barriers such as informal referral systems, closed networks or application processes that favour founders already connected to elite capital circles.
Participation data should be published.
Universities should be connected to the financing system
Nigeria produces research that rarely reaches the market.
One of the six funds could focus on university spin-outs, applied research or deep technology.
That requires different evaluation from ordinary consumer startups.
A scientific venture may take longer to commercialise.
Fund managers need technical expertise.
Universities need clearer intellectual-property policies.
This is an area where development-finance support can be genuinely catalytic.
The programme should avoid overlapping with existing funds
Nigeria already has development-finance schemes, innovation grants and investment programmes.
Before launching six new vehicles, government should map what already exists.
Which programmes are active?
Which are underfunded?
Which have weak performance?
Could some be consolidated?
New funds are not automatically better than fixing existing ones.
Institutional clutter can make access harder.
A public funding directory would help entrepreneurs
FridayPosts would support a verified national directory of startup and small-business financing programmes.
Each entry should list the sponsor, funding type, ticket size, eligible sectors, location requirements, application opening date, deadline, official application link and whether the programme is currently accepting applications.
This would reduce fraud.
It would also stop founders from wasting time on old announcements.
The proposed six funds should enter the directory only when their details are confirmed.
The initiative arrives during a volatile funding market
Nigerian startup funding can swing sharply from month to month because a few large deals dominate totals. That volatility shows why domestic capital matters.
A local financing ecosystem can reduce dependence on global venture cycles.
But public capital should not attempt to recreate Silicon Valley blindly.
Nigeria needs funding models suited to local revenue patterns, currency risk and market depth.
Foreign-currency funding creates another design choice
If JICA or other partners provide foreign-currency capital, the fund must decide how exchange-rate risk is handled.
A startup earning mainly naira may struggle if it effectively has a dollar-denominated obligation.
Equity can absorb some of that risk differently from debt.
Fund design should match the currency of the business.
This is especially important for companies selling mainly into the domestic market.
The funds should publish investment performance annually
Once operational, the programme should disclose how much capital was committed, how much was invested, how many companies received funding, geographic distribution, sector distribution, jobs, revenue growth and follow-on capital raised.
Commercially sensitive information can remain confidential.
Aggregate performance should not.
Taxpayers and partners deserve to know whether the programme works.
Who will qualify?
At this point, no responsible publication should pretend to know the final answer. Applications have not opened and complete criteria have not been published.
That uncertainty should be stated clearly.
What FridayPosts can say is what credible criteria should include: a Nigerian operating nexus, a clear business model, innovation or productivity impact, transparent ownership, basic governance, realistic financial projections, lawful operations and the capacity to use the capital for measurable growth.
The final criteria may differ.
Founders should rely only on official programme documents when they are released.
The announcement is promising because the financing problem is real
Nigeria needs more local risk capital. It needs patient capital for technology and productive businesses. It needs funds that can support companies outside the usual networks.
The partnership with JICA and NSIA could become important.
Its success will depend on details that have not yet been announced.
The six funds should therefore be judged not by the number six, but by whether entrepreneurs can identify them, understand them, apply fairly, receive appropriate capital and build stronger companies.
The financing gap will not be solved by a press release. It will be solved when credible businesses can actually access the money.

Reader conversation
0 approved comments